
Helium Supply Disruption Raises New Semiconductor Manufacturing Risk after Conflict in Iran
Published: 3.16.2026
Key Takeaways
- Helium is a critical semiconductor input because its inert properties and high thermal conductivity help fabs prevent unwanted reactions and tightly control wafer temperatures.
- The clearest immediate semiconductor risk is helium and Qatar produced 64 million cubic meters of helium in 2024 out of 180 million globally, so disruption there removes about one-third of world supply.
- Bromine, shipping, and energy should be treated as rising watchpoints rather than fully proven fab-wide shortages, but the exposure is real enough to matter for procurement planning.
A Specialty Gas Shock Is Now Reaching the Semiconductor Supply Chain
Disruption to helium production in Qatar is emerging as one of the first clear semiconductor supply-chain risks tied to the Iran conflict.
Production linked to the Ras Laffan industrial complex has been halted following regional instability and attacks affecting energy infrastructure, according to reporting from Chemical & Engineering News. The interruption has taken a large portion of global helium capacity offline, raising concerns across industries that rely on the specialty gas.
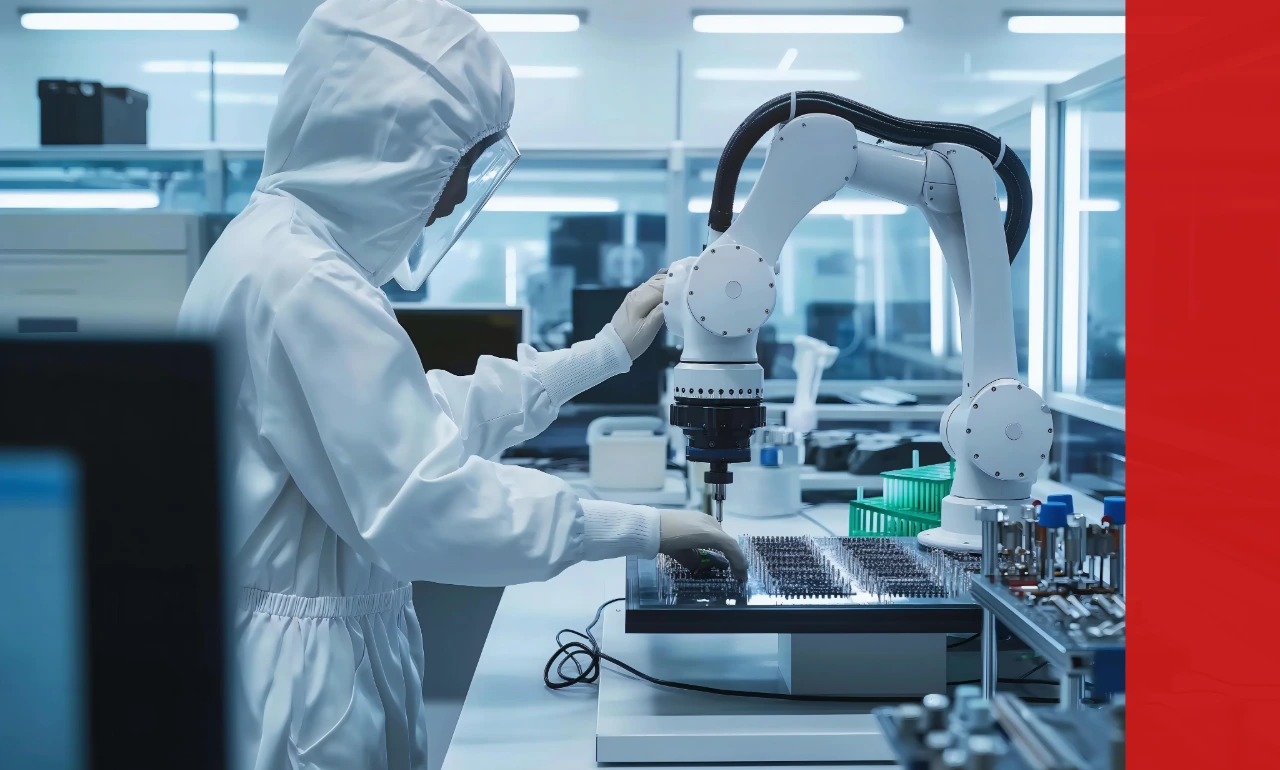
For the semiconductor industry, helium is not a niche input. Its inert chemical properties and extremely high thermal conductivity make it essential for maintaining stable process conditions during high-precision fabrication steps. Semiconductor manufacturers use helium for wafer temperature control, plasma etching, leak detection, and cooling during advanced manufacturing processes.
Industry analysts estimate semiconductor manufacturing now accounts for a substantial share of global helium consumption as chip fabrication continues to expand alongside AI-driven computing demand.
Why Qatar’s Production Matters for the Global Market
The scale of Qatar’s helium production makes any disruption there immediately relevant to global supply.
Data from the U.S. Geological Survey shows Qatar produced roughly 64 million cubic meters of helium in 2024, compared with global output of about 180 million cubic meters and disruptions at Ras Laffan can quickly tighten supply across multiple industries, including semiconductor manufacturing.
Unlike many industrial gases that can be produced on demand, helium is typically recovered as a by-product of natural-gas processing and production depends heavily on a small number of gas fields and processing facilities, creating structural concentration in the market.
Industry experts cited by Chemical & Engineering News say the duration of the disruption will be a critical factor as short outages may be absorbed by inventories held by industrial gas suppliers and semiconductor fabs. However, disruptions lasting several weeks or longer could trigger supply allocation or extended replenishment cycles for high-purity helium used in fabrication facilities.
Secondary Materials Risks Are Emerging
While helium represents the most immediate semiconductor exposure, the conflict is also drawing attention to other specialty materials used in chip production.
TrendForce analysts have pointed to bromine as an emerging watchpoint. Bromine-based compounds such as hydrogen bromide are widely used in semiconductor etching processes, particularly in the production of DRAM and NAND flash.
Supply concentration remains a structural risk. South Korea, one of the world’s largest semiconductor manufacturing hubs, imports the vast majority of its bromine from Israel, highlighting how geographically concentrated certain semiconductor materials supply chains remain.
At this stage there are no confirmed industrywide shortages of bromine, but the situation underscores how geopolitical disruptions can rapidly draw attention to lesser-known inputs critical to chip fabrication.
Shipping and Energy Costs Could Add Pressure
The Strait of Hormuz remains one of the world’s most critical energy corridors. According to the World Economic Forum, more than 80% of the oil and LNG moving through the strait in 2024 was destined for Asian markets including China, Japan, South Korea, and India.
Any sustained disruption in the region has the potential to increase shipping costs, insurance premiums, and rerouting expenses for global freight. Those pressures can ripple through semiconductor supply chains that depend heavily on Asia-bound logistics networks for specialty gases, chemicals, and manufacturing equipment.
Semiconductor fabrication plants are among the most power-intensive manufacturing facilities in the world. Analysts estimate that Taiwan Semiconductor Manufacturing Company alone accounts for close to 9% of Taiwan’s total electricity consumption. Rising energy prices tied to Gulf instability could therefore add additional cost pressure across the semiconductor ecosystem.
What the Industry Should Watch Next?
For now, the disruption appears manageable for major manufacturers.
TrendForce reports that some semiconductor companies, including SK hynix, have secured sufficient helium inventory and diversified supply arrangements, helping shield near-term production from immediate impact.
However, the situation highlights how quickly geopolitical tensions can propagate through semiconductor supply chains via specialty gases, process chemicals, logistics corridors, and energy costs.
Procurement teams should monitor several early indicators of escalation in the coming weeks, including tightening helium supply from industrial gas providers, longer lead times for high-purity gas deliveries, and potential surcharge activity tied to logistics or energy costs.
Even if the current disruption proves temporary, it reinforces a broader structural lesson for the semiconductor industry that often rely on highly concentrated global supply chains.
Need help reducing sourcing risk for semiconductor components and critical materials?
IBS Electronics helps procurement teams identify alternative sources, monitor market shifts, and secure supply faster when market conditions tighten.


